

Trump Accounts: Official App
Department of the Treasury
- 4.8
- 448.00 Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
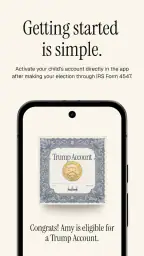
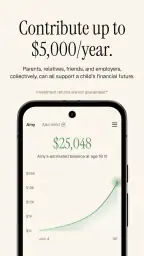
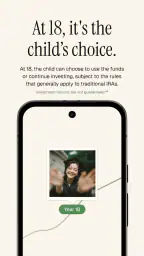
Trump Accounts: Official App Pros and Cons
Pros
- Official source for checking Trump Accounts program information
- Provides clear eligibility and enrollment guidance
- Useful updates for participating families and guardians
- Simple interface focused on essential account details
- Helps users find relevant government resources and support
Cons
- Availability may depend on eligibility and account enrollment status
- Some features may redirect users to external government websites
- Information can change as program rules and funding are updated
- Limited usefulness for users outside the United States
- May require personal details or identity verification for certain services
 Analysis by All-app
Saving for a child’s future usually sounds simple until the practical questions begin: where should the money go, who manages it, and how can a parent keep the process organized without turning it into another complicated financial project? Trump Accounts: Official App is built around that specific concern. It is a free finance app from the Department of the Treasury, focused on helping families engage with Trump Accounts rather than acting as a general-purpose budgeting, banking, or investing tool.
After spending time with it, my main impression is that its value depends less on how often you open it and more on whether you need a dedicated place to follow this particular child-focused financial arrangement. The app’s central idea is narrow, which is both its appeal and its limitation. It does not try to replace your bank, household budget, or broader investment planning. Instead, it gives the future of a child a more visible place in your financial routine.
The store summary, “Invest in your child’s future,” captures the intended audience, while the short description, “Trump Accounts,” makes the app’s purpose unusually direct. It is aimed at people who want to understand and manage their involvement with these accounts through an official mobile experience. For a parent or guardian who would otherwise rely on scattered paperwork, saved browser pages, or occasional checks, that focus can make the subject feel more manageable.
Why the account-focused approach matters
The most important capability here is not a long list of financial tools. It is the app’s role as a focused access point for Trump Accounts. That distinction matters because many finance apps overwhelm users with spending charts, credit offers, market news, bill reminders, and unrelated products. This one is easier to judge: if you need a clear connection to a child’s account, it has a reason to be on your phone; if you want a complete household finance dashboard, it is unlikely to be enough by itself.
I found that narrow purpose helpful when thinking about family money. A child’s long-term account can easily disappear behind everyday expenses. Rent, groceries, school costs, and emergency bills demand attention now, while a future-focused account feels distant. An app dedicated to that account creates a separate mental checkpoint. Even when there is no urgent transaction to make, opening the app can remind you that this money has a different purpose from the balance in your checking account.
That separation is one of the less obvious strengths. A standard banking app may show many balances at once, but it does not necessarily encourage you to think about one particular child’s future. A budgeting app may help you plan contributions, yet it may not be the official place for the account itself. The Treasury’s app sits closer to the subject it represents, which can reduce the chance that the account becomes an afterthought.
At the same time, I would not mistake focus for financial advice. The app is useful for engaging with the account, but families still need to make their own decisions about household priorities, affordability, and long-term planning. If opening or funding an account would put pressure on essential bills, the app’s existence does not change that tradeoff. Its job is to make the account easier to follow, not to decide what your family can safely afford.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Using it as a family routine
A practical way to use the app is to attach it to an existing money habit. For example, a parent might check it after reviewing monthly bills, or a guardian might use it during a regular family financial review. The useful insight is that the app works best as a reminder and reference point, not as something that requires constant attention. A long-term child account should not encourage impulsive checking or emotional reactions to every small change.
I also think it can help couples and co-parents keep the topic visible. When financial responsibilities are divided, one person may handle daily banking while another thinks about longer-term savings. A dedicated app gives both people a common subject to discuss, even if they use it at different times. That can be more effective than assuming everyone remembers the same account details from an old conversation.
For grandparents or other relatives, the situation is more nuanced. The app may be relevant if they are directly involved with a child’s account, but it should not be treated as a universal family gift-planning tool. Before relying on it, I would first clarify who is responsible for the account and what role each adult has. The app’s focused design does not remove the need for clear family communication.
What using it feels like in practice
In everyday use, I would approach this as an official account companion rather than a traditional banking app. The first step is understanding whether the child and the adult using the app fit the account’s intended situation. Once that is clear, the app becomes most useful when you use it to keep the account connected to a real plan: why the money is being set aside, who is monitoring it, and when the family will review it again.
One realistic scenario is a parent who receives a reminder to think about the child’s future while preparing the household budget. Instead of mixing the account into a general savings category, the parent opens the Treasury app, checks the relevant account information, and then decides whether the family’s current finances support the next step. The important benefit is not speed alone. It is the clear separation between an account for a child’s future and money intended for immediate household needs.
Another useful workflow is to use the app before speaking with another adult involved in the child’s finances. Rather than discussing the account from memory, you can review the current information first and then have a more precise conversation. That reduces misunderstandings, especially when one person assumes a contribution or action has already happened and the other does not.
I would also keep expectations realistic about mobile convenience. An official app can make access more comfortable, but it does not guarantee that every financial question can be answered instantly. Some situations still require careful reading, identity checks, or support through the appropriate official channel. If an issue affects ownership, eligibility, or the handling of money, I would slow down and verify each step instead of treating the app like a one-tap solution.
The app’s current version is 2026.34.0, and it supports devices running Android 7.0 or later. That broad operating-system requirement makes it approachable for people who do not replace their phone frequently. Still, I would keep the app updated when updates are available, particularly for a finance product. A financial app deserves the same care as any other account access tool: use a device you control, keep the phone protected, and avoid treating a public or shared device as a safe place for sensitive activity.
The strongest scenario: making a child’s account visible
The best use case is a family that already wants to build a long-term financial habit for a child but needs a dedicated way to keep the account in view. In that situation, the app’s focused purpose is a genuine advantage. It gives the account a place in the same digital environment where people already manage important parts of life, without forcing the account into a general banking dashboard.
Imagine a household with irregular income. The parents do not want to promise the same contribution every month, because some months include medical costs or school expenses. They can still use the app as a review point: check the account, look at the wider household situation separately, and decide responsibly when an additional contribution makes sense. That is a better use of the app than turning it into a pressure mechanism.
It can also suit a family preparing to teach a teenager about long-term money. The adult can use the account as a starting point for conversations about delayed benefits, saving, and the difference between money for today and money intended for later life. The app itself does not replace financial education, but its single-purpose context can make those conversations less abstract.
For a child who has more than one involved adult, the account can become a shared reference rather than a vague promise. However, I would recommend agreeing in advance on who checks it, who communicates changes, and how decisions are discussed. Technology can make information easier to reach, but it cannot resolve family disagreements about responsibility.
Where the tradeoffs become clear
The biggest limitation is the app’s narrow scope. If you want spending analysis, automatic bill tracking, debt management, investment research, or a complete view of several financial institutions, you will need other tools. A general bank app is better for everyday transactions, while a budgeting app is better for seeing how income is allocated across a household. This app should complement those tools, not be expected to replace them.
There is also a difference between visibility and control. Seeing an account in an official app can make it easier to stay informed, but it does not mean every user has the same authority or responsibility. Parents, guardians, and other participants may have different roles. I would avoid assuming that an app screen alone settles who can act on the account or how decisions should be made.
Another tradeoff is emotional. A child-focused account can encourage hopeful, long-term thinking, but families may feel disappointed if they expect immediate financial improvement. The benefit of this kind of account is tied to patience and consistency. If your priority is building an emergency fund for next month, paying down expensive debt, or covering an urgent household shortfall, a general savings or banking solution may be the more responsible first choice.
The app is also not the right choice for someone who wants a broad educational experience before taking any action. Its purpose is account-focused, so a beginner looking for detailed lessons on budgeting, investing, taxes, and retirement will probably need a separate educational resource. I appreciate that the app does not need to pretend to be everything, but users should choose it with that boundary in mind.
Privacy and device habits deserve attention as well. Any finance app should be used with a secure screen lock and careful account protection. I would not install it casually on a phone shared with children or relatives, and I would review the information shown on screen before handing the device to someone else. Those are ordinary precautions, but they matter more when the app relates to a child’s financial details.
How it compares with familiar alternatives
Compared with a bank’s mobile app, this Treasury product is more specialized. A bank app usually wins for moving money, checking everyday balances, and managing the rest of your financial life. The Trump Accounts app is more useful when the account itself is the subject you want to follow. If you only need routine banking, opening another finance app may add unnecessary friction.
Compared with a budgeting app, the difference is even clearer. Budgeting tools help answer questions such as whether your family can afford a contribution and how that contribution fits alongside bills. This app is better suited to keeping the child-focused account visible and connected to its official purpose. I would use a budget for the decision-making context and this app for the account-specific follow-up.
Compared with a spreadsheet, the app offers a more direct and less customizable experience. A spreadsheet can combine household income, school expenses, savings goals, and contributions in one personal model. That flexibility is valuable for detail-oriented users. The tradeoff is that a spreadsheet depends on manual upkeep and can drift away from the account’s actual status. The official app is less flexible, but potentially more appropriate as the reference point for the account itself.
Compared with paper records, the app is easier to revisit when a family wants a current digital reference. Paper can still be useful for keeping personal notes, especially when several adults are coordinating plans, but it should not become the only place where important account information is recorded. I prefer using personal notes to track questions and goals while relying on the official app for the account-related view.
Who benefits most from the focused design
The strongest audience is a parent or guardian who wants a straightforward way to keep a child’s long-term account in the family’s regular financial awareness. It is also a reasonable fit for someone who dislikes sorting through a large banking dashboard just to find one important account. The app’s free price removes a direct purchase barrier, which makes trying it more practical for families that want to see whether the official workflow suits them.
Its audience is not limited to finance experts. The Everyone content rating makes it broadly approachable from an age-classification perspective, although the account itself still involves adult financial responsibility. A person does not need to be an investing specialist to benefit from a clear account reference, but they should be willing to read carefully and make decisions based on their own circumstances.
The app has also attracted a substantial user base, with over five hundred thousand installs, and its average rating is 4.8 from around three thousand ratings. I treat those figures as encouraging signs of interest and user satisfaction, not as a guarantee that every family will have the same experience. The published review count is around four hundred, which gives additional context but still cannot replace trying the app with your own account situation.
I would recommend skipping it if you are searching for a complete personal finance center, a detailed investment research platform, or an app that automatically solves your household savings decisions. In those cases, your bank, budgeting software, or a qualified financial professional may be more useful. Installing this app will not make an unsuitable contribution affordable, and it will not replace a broader plan.
For everyone else, the decision is fairly simple: if Trump Accounts are relevant to your family, an official, dedicated app is more sensible than forcing the subject into an unrelated tool. If they are not relevant, there is little reason to add another finance app just because it has a high rating.
My final take after using it
I see Trump Accounts: Official App as a focused companion for one financial responsibility, not as a replacement for banking or budgeting. Its real strength is making a child’s future account easier to keep visible, discuss, and review within a family’s normal routine. That may sound modest, but long-term financial habits often fail because they disappear from attention rather than because people lack good intentions.
I like the fact that the app’s purpose is easy to understand. The Department of the Treasury is the developer, the app is free, and the experience is aimed at a clearly defined account type. Those qualities make it a practical starting point for eligible families who want an official mobile reference instead of relying entirely on memory or scattered records.
My recommendation is strongest for parents and guardians who will use it alongside a household budget and sensible financial priorities. Check it during planned reviews, use it to support clear conversations with other responsible adults, and resist treating it as a reason to contribute beyond your means. The best result comes from turning visibility into a calm, repeatable habit—not a rushed financial decision.
Frequently Asked Questions
What is the Trump Accounts official app used for?
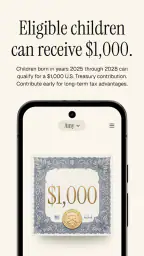
The Trump Accounts official app is intended to help eligible users and families learn about, access, and manage information related to Trump Accounts, a government-supported investment savings program for qualifying children. Depending on your eligibility and the app’s available features, you may be able to review enrollment guidance, submit required information, check account details, and follow updates. Always confirm the app’s current functions through its official listing and government website.
Who can use Trump Accounts, and am I eligible to open one?
Eligibility depends on factors such as the child’s age, citizenship or residency status, birth date, and the requirements established by current federal legislation and program guidance. Parents, legal guardians, or other authorized individuals may need to provide identifying information and documentation. Because rules can change and individual circumstances differ, use the app’s eligibility information as a starting point and verify your situation through official government resources before applying.
Is the Trump Accounts app safe to download and use?
For safety, download the application only from a verified official source, such as the Apple App Store, Google Play, or a government website that links directly to the correct listing. Check the developer name, privacy details, permissions, reviews, and update history before installing. Be cautious of similarly named apps, unsolicited messages, or websites requesting sensitive information. Never share account credentials or identity documents through unofficial channels.
What personal information may the app request?
An official account-management application may request information needed to verify identity, confirm eligibility, create or access an account, and communicate with authorized users. This could include names, dates of birth, Social Security or taxpayer identification details, contact information, and documentation, depending on the process. Review the app’s privacy policy before submitting anything, use a secure connection, and make sure you understand how your data is collected, stored, and shared.
Does using the app guarantee that my child will receive money or investment growth?
No. Installing or using the Trump Accounts official app does not automatically guarantee enrollment, government contributions, eligibility, investment returns, or future account value. Benefits depend on program rules, successful verification, available funding, contribution requirements, and other conditions. Investment accounts can also involve market risk, fees, and changing returns. Read all official disclosures carefully and consult a qualified financial professional if you need personalized advice.


